Emerging managers
№ 005
The pitch gets you meeting one. The LP decides later.
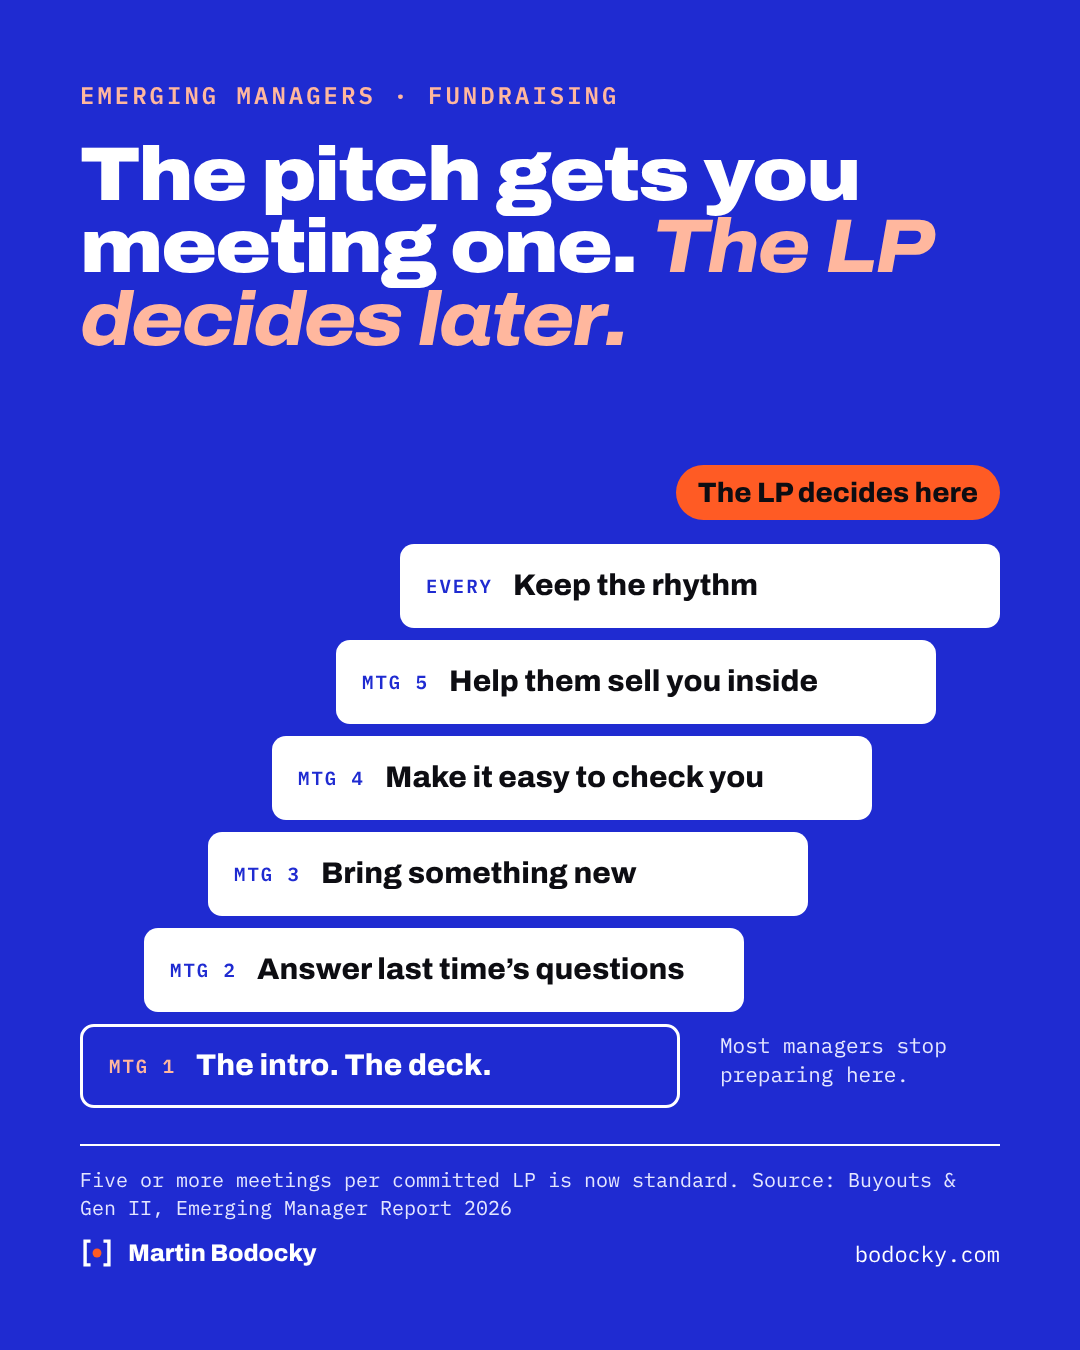
Most emerging managers prepare for the first LP meeting like it's the final exam 📚
Deck polished. Story rehearsed. Numbers memorised.
Then I learned the uncomfortable part: almost no LP decides in meeting one.
Five or more meetings per committed LP is normal and always was.
Don't let anyone convince you that you would fall in love and get your agreement signed after a short time (unless you get them into FOMO 😱, but about that I will write in the future).
The intro gets you into the room. Meetings two to five get you the commitment.
What actually moved the LPs I worked with:
1.) Answer what they asked last time. Come back with the answer, not the same deck.
2.) Bring something new every time. A deal closed, a portfolio update, a number that moved.
3.) Make it easy to check you. References, co-investors, your last investor report. Offer them before they ask.
4.) Help them sell you inside their own house. A family office principal has a family. A fund-of-funds has a committee. Give them the one page they can forward 📄.
5.) Keep the rhythm. Same update, same cadence, committed or not.
Honestly, this is where many great European managers lose the raise. Brilliant investors.
Nobody ever taught them to sell themselves.
The raise isn't won in the pitch. It's won in the follow-up 🔁
Curious:
➡️ GPs, in which meeting did your first LP actually decide?
➡️ LPs, what did you need to see after meeting one?