Emerging managers
№ 006
The clock nobody measures
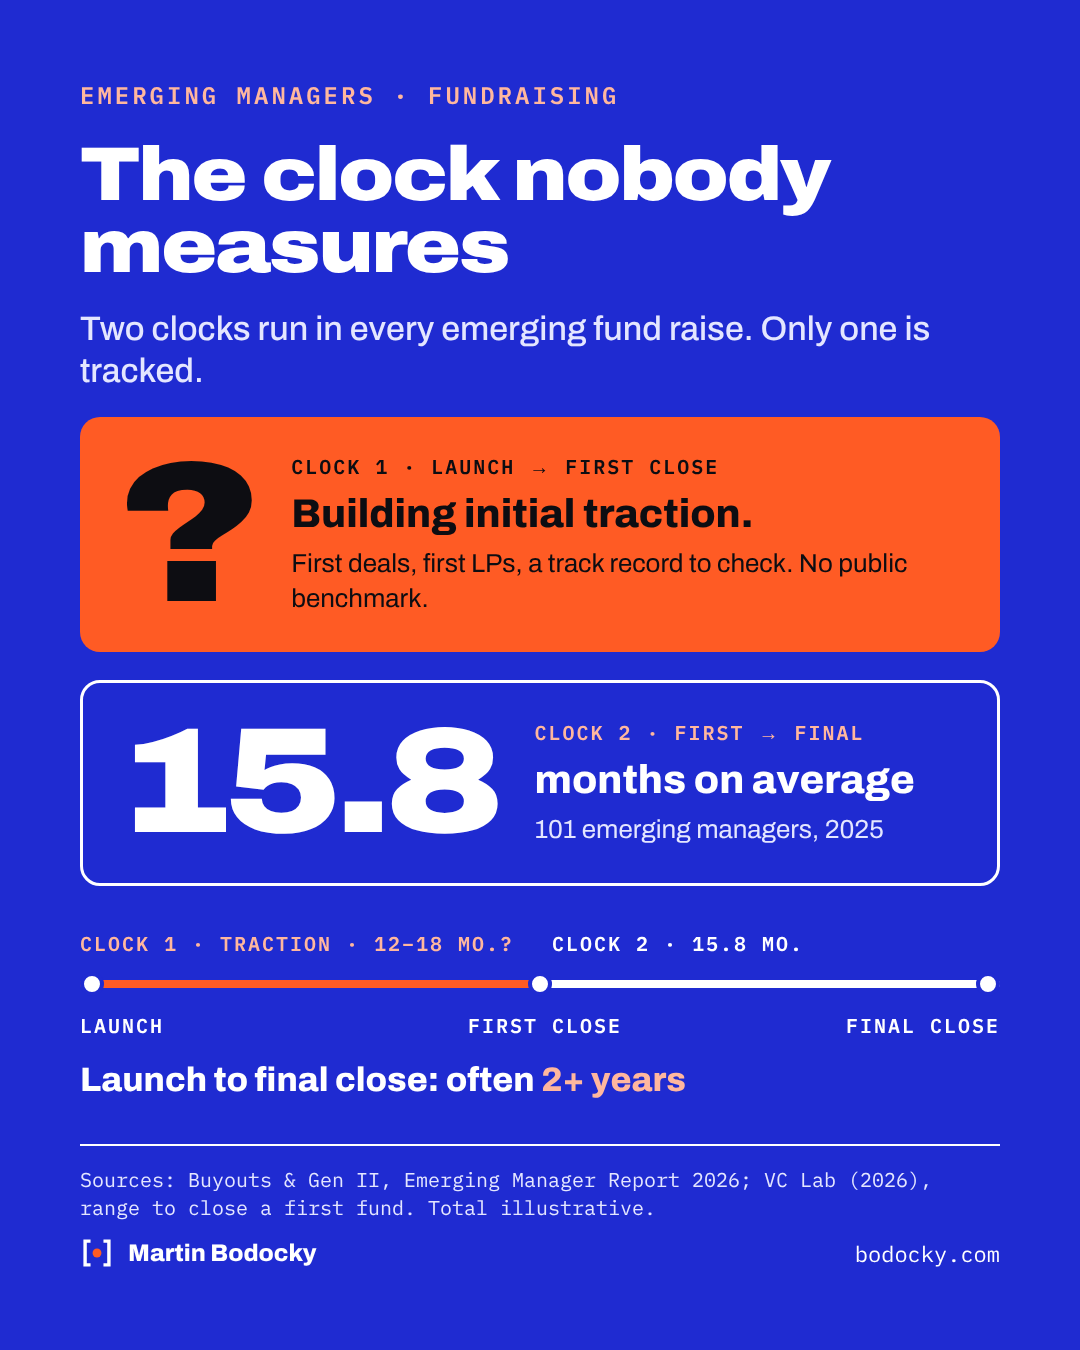
There are two clocks in every emerging fund raise ⏱️
The industry only measures one of them.
Clock 2: first close → final close. Well documented. Emerging managers took 15.8 months on average in 2025, down from 18 a year earlier (Gen II & Buyouts, 101 managers surveyed).
Clock 1: launch → first close. Nobody publishes a benchmark for it, because it is not just fundraising.
It is the time you spend building initial traction:
→ first deals, often through SPVs or a warehoused portfolio
→ first LP relationships, built meeting by meeting
→ a track record an LP can actually check
→ the operational setup an LP expects before committing
VC Lab, which works with hundreds of new funds, says 12 to 18 months is a common range just to close a first fund.
And honestly, clock 1 is the brutal one.
Every LP asks: who else is in? Every meeting starts from zero. You burn savings while you prove you are worth backing.
The good news: everything you build in clock 1 shortens clock 2. Every SPV, every update, every LP who has already wired you money turns "why you?" into "how much?" 🔓
Put the two clocks together and an emerging fund can easily spend more than two years between launch and final close. Most of the risk sits in the first one, and that is where most funds that never close get stuck.
Yesterday I wrote about the meetings after the intro. Tomorrow: why emerging funds stall before the first close, and what the managers who get there do differently.
➡️ GPs: how long did your clock 1 take, and what traction moved your first LP?